A single accident on your property could cost you tens of thousands in medical bills and legal fees. Yet most Singapore homeowners overlook personal liability insurance, the coverage that protects you when someone is injured at your home or by you or your family.
Personal liabilities insurance is not a luxury. It is the financial shield that stands between an everyday mishap and a devastating loss of savings. And contrary to what many think, it is often already included in Singapore home insurance plans, such as our Home Protect360.
In this guide, we explore five real-life scenarios where personal liabilities insurance can save families from financial ruin — and how to make sure you have the right cover.
What is Personal Liabilities Insurance?
Personal liabilities insurance is a type of coverage that protects you if you are found legally responsible for causing bodily injury to another person or damaging their property. Hence the term “personal liability.” You are liable for the damage to the other party, and are required to compensate them with a specified amount to cover said damage.
A personal liabilities insurance plan covers the financial costs associated with these claims. It pays for the claimant’s medical bills, repair expenses, and your legal defence costs up to the limits stated in your policy.
Essentially, it ensures that an accident does not result in a devastating financial loss that could jeopardise your savings and assets.
So, what are the common situations in which personal liabilities insurance can help?
Scenario 1: Slip-and-Fall Accidents On Your Property
As a homeowner, you have a responsibility to maintain a safe environment for your guests.
If a visitor suffers an injury due to an overlooked hazard on your premises, you can be held liable for their medical recovery.
Imagine you invite your neighbours over for a weekend dinner party. Earlier that afternoon, you washed the veranda floor, leaving a small patch of wet tiles. A guest walks outside, slips on the wet surface, and fractures their wrist. The injury requires surgery and will keep them out of work for weeks.
Because the hazard occurred on your property, you can face a claim for their medical expenses and lost income. Your personal liability policy steps in to pay these costs, saving you from paying thousands of dollars out of your own pocket.
Scenario 2: Pet Bites and Injury to Guests
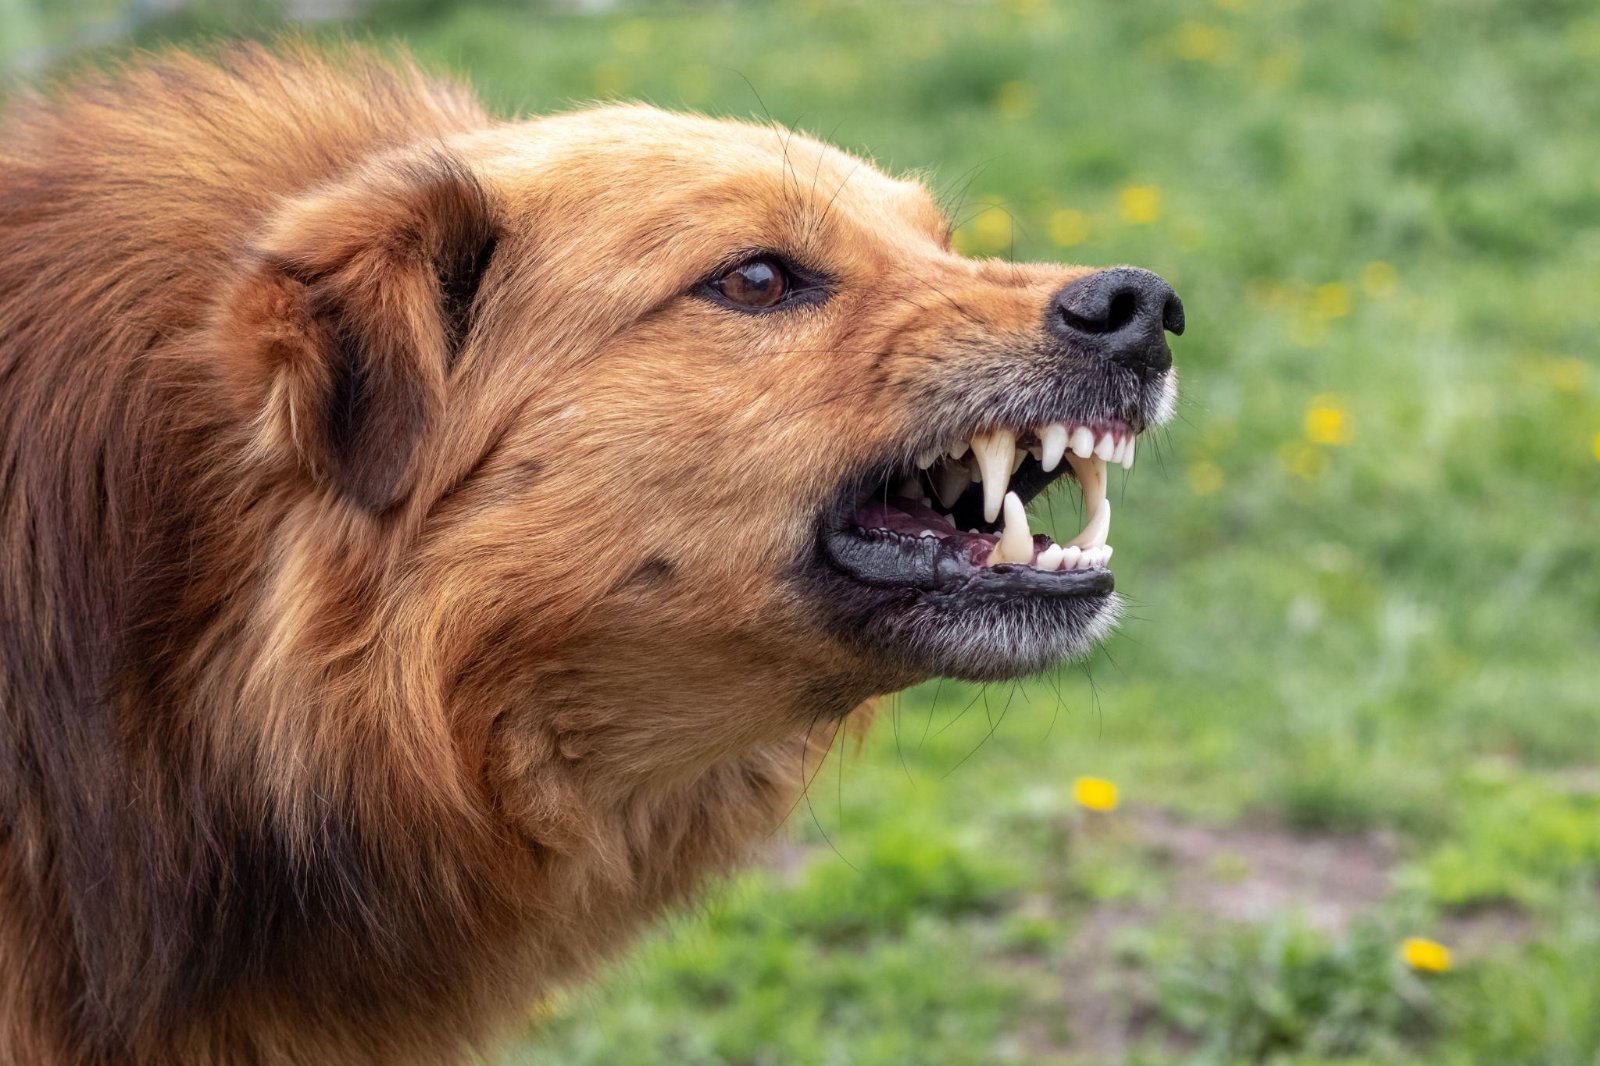
If your dog or cat scratches or bites a guest, you may be held legally responsible for the consequences. Even if your pet is fully vaccinated, the injured guest will still need to clean the wound, seek medical attention, and may require a tetanus booster, antibiotics, or follow-up consultations depending on the severity of the bite.
As the owner of the dog, you’re liable for the injuries the guest sustained. This liability will depend on how serious the bite was and whether animal-transmitted diseases have been observed.
However, your pet can still bite even when they’re not in the home. Let’s say a stranger approaches to pet your dog, but a sudden motorbike backfire startles the animal. Your dog snaps and bites the stranger’s hand, requiring emergency clinic treatment and stitches. The injured individual sends you the medical bills and demands compensation for their pain and suffering.
Your liability policy covers these medical bills, protecting your personal finances as you resolve the incident.
Scenario 3: Injury and Property Damage Caused by Your Children
Children are full of energy, and their active play can sometimes lead to accidental destruction.
Parents are generally held responsible for their children’s actions, meaning a simple game at home can quickly turn into a costly dispute with the neighbours.
For example, your children are playing football in your back garden. One of them kicks the ball too hard, sending it over the fence. The ball crashes through your neighbour’s expensive conservatory window, shattering the glass. The neighbour requests that you cover the full costs of replacement and repair. Rather than dipping into your savings to settle the bill, your personal liability coverage can respond to the property damage claim.
Scenario 4: Injury and Property Damage You Caused While Travelling
You can clumsily cause property damage or injure someone while you are away from home on a family holiday. Thankfully, comprehensive liability protection can follow you across the globe.
Suppose you are on a family holiday in London, checking into a busy hotel. While walking through the crowded lobby, you turn around, and your suitcase trips an elderly tourist. The tourist falls and suffers a hip injury that requires immediate hospitalisation. Since your accidental movement caused the injury, you may be liable for the cost of international medical care, which can be considerable.
Our personal liability protection helps cover these expenses so that an unfortunate incident does not derail your holiday or your finances.
Scenario 5: Injury You Caused To Others While Taking Part in Recreational Sports
Let’s say you tee off, but your shot hooks to the right, flying toward an adjacent fairway. The ball strikes another golfer directly in the face, causing dental damage. Because your stray shot caused direct bodily harm, you are held responsible for their dental care and medical treatments.
Your personal liability insurance covers the claim, providing the funds needed to support the victim’s medical recovery.
Similar claims can arise in other recreational activities where accidental injury to others is highly likely, such as outdoor or combat sports. Take note that liability arising from professional sports, organised competitions, or the use of aircraft and watercraft is typically excluded from standard personal liability cover. We recommend reviewing your policy wording or speaking with us if you regularly take part in these high-risk sports.
Why Aren’t Car-Related Accidents Covered by Personal Liability Insurance?
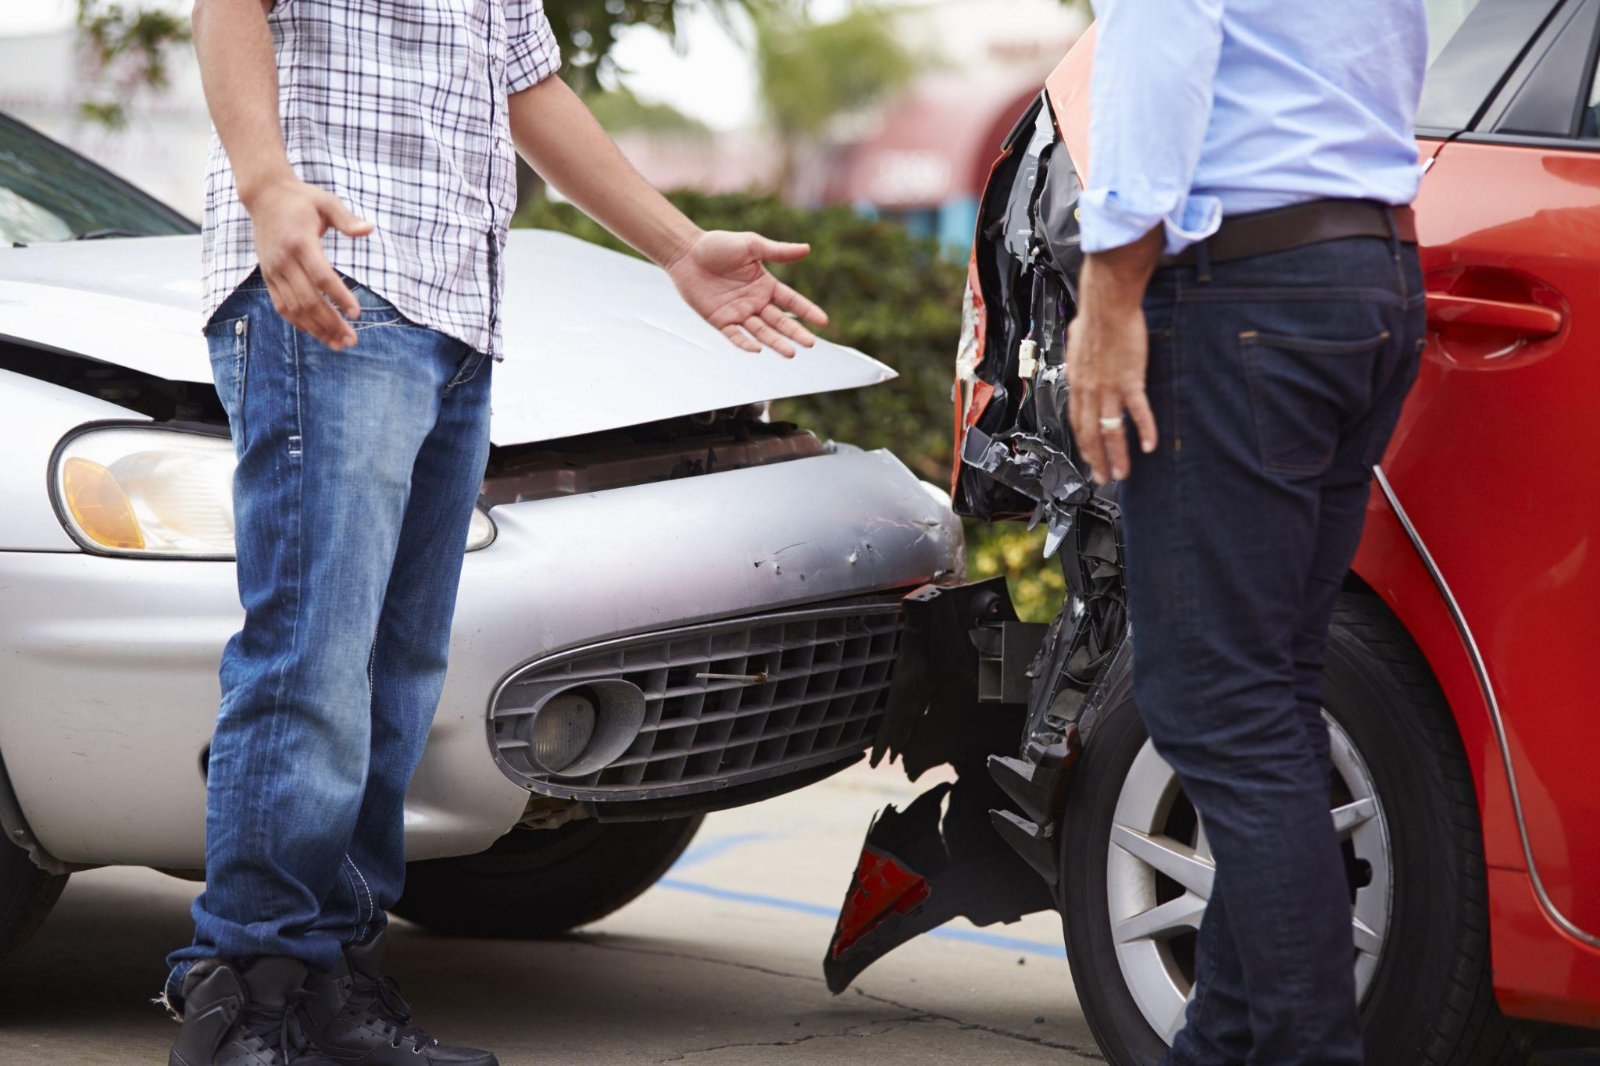
Personal liability insurance covers everyday lifestyle risks, but it explicitly excludes motor vehicle accidents.
Operating a vehicle on public roads carries a higher level of risk. Because of this, car insurance is a separate policy and carries higher premiums. Governments worldwide, including Singapore, mandate that all drivers must hold a separate, dedicated motor insurance policy.
Your car insurance includes a distinct third-party liability section designed specifically for road accidents.
Personal liability insurance, on the other hand, covers you as an individual pedestrian, homeowner, parent, pet owner, etc., but the moment you get behind the steering wheel, your car insurance takes over.
Can Home Insurance Cover Personal Liability Claims on My Property?
Yes, they can.
Many homeowners do not need to hunt for a standalone liability policy. Comprehensive home insurance plans often include personal liability protection as a core feature.
For example, our Home Protect360 plan includes worldwide personal liability cover of up to S$500,000 (excluding the USA, Canada, and Japan). This protects you not only at home, but also when you are out with your family, travelling, or taking part in recreational activities.
Get a Comprehensive Personal Liability Insurance Policy Today!
Protecting your family and your hard-earned assets means preparing for the legal risks that may arise in everyday life.
At HL Assurance, we designed Home Protect360 to provide the complete security you need. With up to S$500,000 in worldwide personal liability coverage (excluding the USA, Canada, and Japan), we have your back if an accident occurs. Beyond liability coverage, our plan safeguards your furniture, renovations, and valuables and provides access to our home assistance concierge hotline for urgent plumbing or electrical issues.
Do not leave your financial future to chance. When in doubt, you can chat with HLAS to find out more. Please direct your enquiries to our service hotline at 6702 0202 or email service@hlas.com.sg.
Frequently Asked Questions
Does personal liability insurance cover incidents that happen outside Singapore?
It depends on your policy. Our Home Protect360 plan provides worldwide personal liability coverage of up to S$500,000 (excluding the USA, Canada, and Japan), so you remain protected against third-party claims even when you are travelling overseas or taking part in activities abroad. Always check your specific policy wording for the geographical scope.
Does personal liability insurance cover injuries to people who live in my home?
No. Personal liability insurance is strictly third-party coverage. It is designed to protect you against claims made by outsiders, such as guests, delivery personnel, or neighbours. It does not cover bodily injuries sustained by you, your spouse, your children, any relatives, or domestic helpers residing with you.
Are injuries to my domestic helper covered under this policy?
No, domestic helpers are excluded from standard personal liability coverage. Under Singapore’s Ministry of Manpower (MOM) regulations, employers must purchase Personal Accident insurance (minimum S$60,000) and Medical insurance (minimum S$60,000 annual limit) for their domestic helpers. Most insurers, including HL Assurance, bundle these into a single maid insurance plan.
Author
HL Assurance (HLAS) is a licensed general direct insurer in Singapore and a member of the General Insurance Association (GIA). Backed by the Hong Leong Group — a diversified conglomerate spanning banking, financial services, and investments across Asia, Europe, and beyond — HLAS offers a wide range of personal and commercial insurance products, including travel, motor, home, maid, and personal accident insurance. With a track record of award-winning service and a focus on digital accessibility, HLAS is dedicated to helping individuals and businesses in Singapore protect what matters most.

 Malaysia
 Hong Kong