It’s not just the home’s physical structure that needs to be insured.
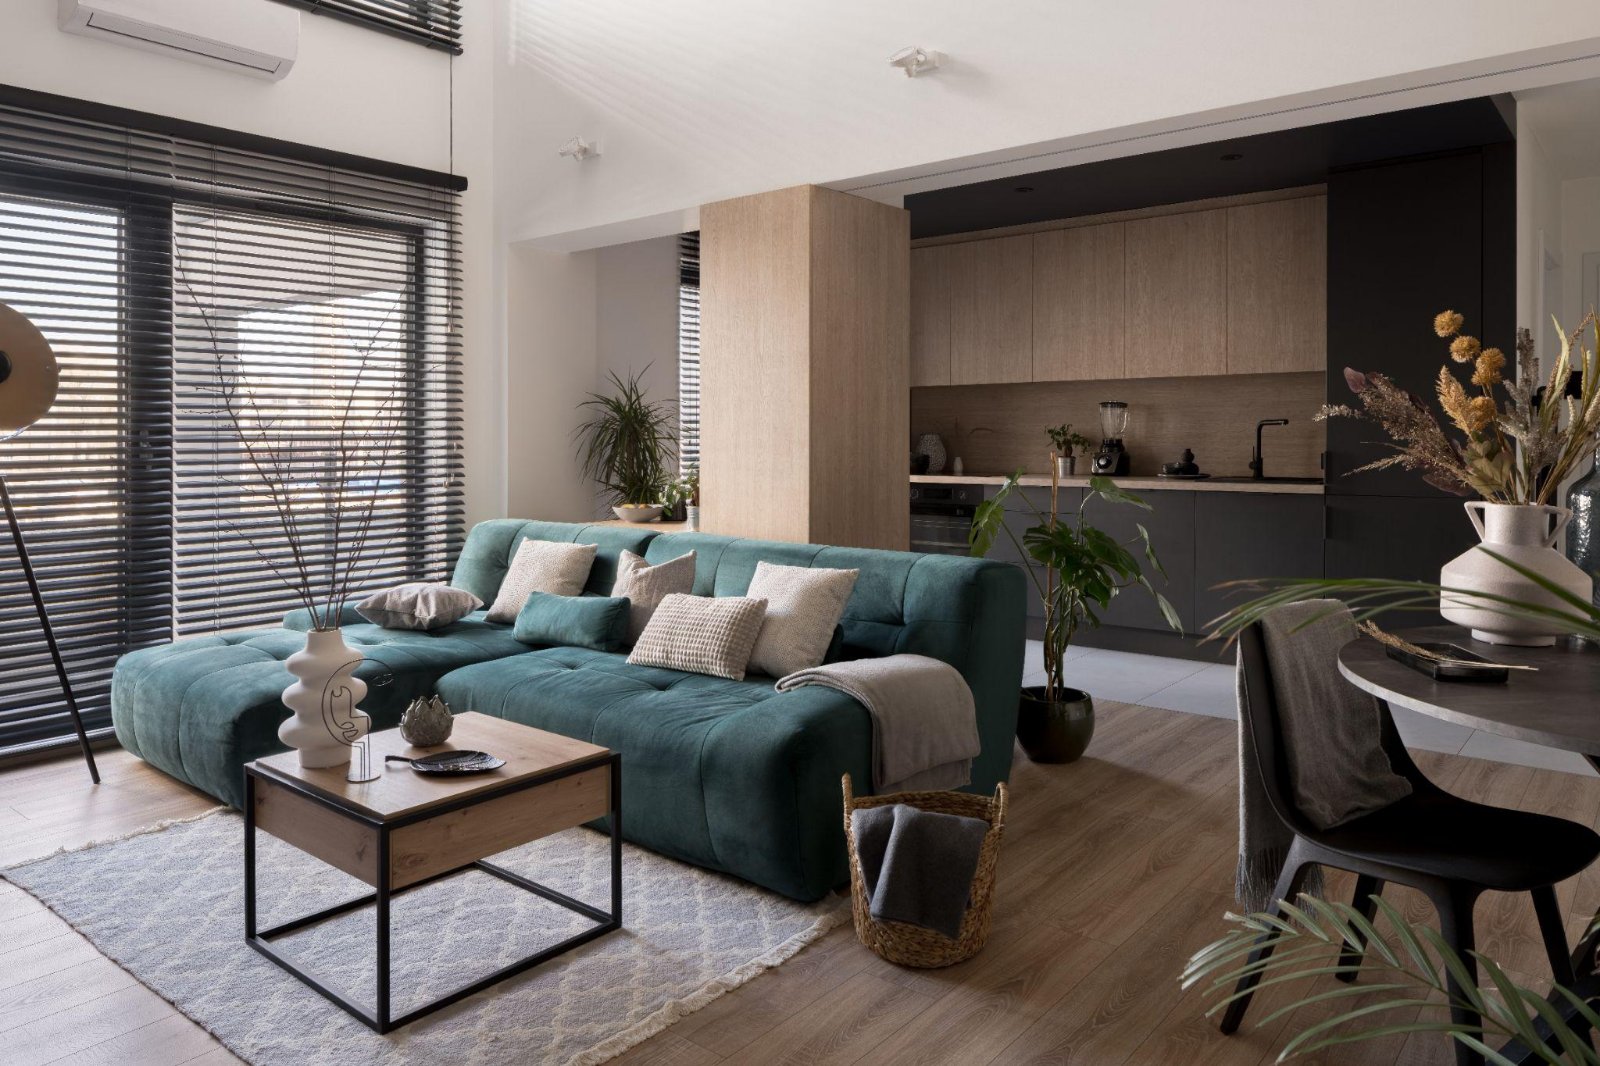
When you buy a house, you spend time and money turning it into a comfortable living space. You purchase furniture, fill your rooms with appliances to make it more functional, and accumulate personal items that make the space yours.
All these possessions are a major financial investment. If an unforeseen event occurs, replacing everything at once can place considerable strain on your savings.
This is why house contents insurance is vital protection for your household assets, alongside home insurance in Singapore. In this guide, we at HL Assurance will break down everything you need to know about this policy so you can make informed decisions for your home.
What is Contents Insurance?
Contents insurance is a policy designed to protect the possessions inside your property.
This includes everything from your kitchen appliances and living room sofas to your clothes and precious jewellery.
This type of coverage ensures that if your items are damaged, destroyed, or stolen, you can receive financial compensation to repair or replace them. It acts as a safety net for your everyday possessions, helping to ensure that an unexpected incident does not result in high out-of-pocket costs.
What Events do Contents Insurance Cover?
When these events happen, you can file a claim to recover your financial losses. Let us look at the primary events that trigger your coverage.
Theft and Vandalism
If someone breaks into your house and steals your belongings, house contents insurance helps cover the loss.
This coverage applies to stolen electronics, personal goods, and valuables.
Furthermore, if an intruder damages your property during a break-in, such as tearing your curtains or defacing your walls and furniture, the policy handles the repair costs.
Fire
A standard contents insurance policy provides robust protection against fire damage. If an electrical fault or a cooking accident causes a fire, we will pay to replace your damaged items.
The coverage also extends to damage caused by smoke (e.g., wall discolouration, tainting of throws and upholstery) and the water used by emergency services to extinguish the flames.
Weather Events
In Singapore, heavy monsoon rain and flash floods can seep into ground-floor units, while leaks through windows or rooftops can damage carpets, furniture, and electronics. Strong winds during heavy storms can also break windows and expose your belongings to water and debris.
When unforeseen weather events cause sudden damage to your indoor possessions, your policy responds.
Items Covered by Contents Insurance
Here are the main groups of items that we protect under a standard contract.
Electronics and Appliances
Our homes are filled with valuable technology that we use for work and entertainment. They’re also some of our more costly and valuable possessions.
Under this category, your policy covers:
- Large goods like refrigerators, washing machines, ovens, and dryers.
- Entertainment equipment such as television sets, gaming consoles, and sound systems.
- Your laptops and desktop computers
Because these items are expensive to replace, having them insured ensures that a sudden power surge or water leak will not ruin your finances.
Furniture and Furnishings
This group includes items such as beds, wardrobes, dining tables, chairs, and sofas.
It also extends to smaller decorative furnishings, including carpets, curtains, cushions, and light fixtures that are not permanently attached to the building.
If a pipe bursts and floods your bedroom, our contents policy can help manage the replacement costs. This allows you to restore your home to its condition before the incident.
Clothing and Personal Effects
Contents insurance covers your everyday garments, such as shoes, winter coats, and formal wear.
Additionally, it protects personal effects, which are items you carry or wear, such as bags, watches, and jewellery.
While these items are protected when stored in your home, remember that luxury items may require special declarations.
How Contents Insurance differs from Home Insurance
In Singapore, “home insurance” is often used as a broad umbrella term that can refer to either building or contents protection, which is why the two are often confused.
However, there is a distinct line between building protection and contents protection.
Items Covered
The policy that protects the physical brick-and-mortar shell of your house is more accurately called fire insurance. It covers the roof, walls, floors, foundations, and permanent fixtures like fitted bathroom suites and kitchen cabinets. For HDB flat owners, this protection is provided through the mandatory HDB Fire Insurance Scheme.
In contrast, contents insurance covers the movable items you place inside that shell.
For example, if a fire damages your kitchen, your building insurance will repair the walls and the fitted countertops. Meanwhile, contents insurance covers your freestanding microwave, dishes, and dining table.
Who Benefits From It
If you are a landlord who owns a flat but rents it out to tenants, you primarily need building insurance to protect your real estate asset. You do not need contents insurance for the tenant’s belongings, as those are their responsibility.
If you are a tenant renting a home, you do not need building insurance because you do not own the physical building. Instead, you need house contents insurance to protect your personal belongings inside the flat.
For homeowners who live in their own property, both forms of coverage are necessary. You want to protect the house itself and the lifestyle assets you have gathered inside it.
Crucial Limitations Policy Holders Must Know about Contents Insurance
While contents insurance offers excellent protection, policies have explicit parameters and boundaries.
Single Article Limit
Every policy has a cap on the maximum amount we can pay out for a single item. This is called the single article limit.
Under our Home Protect360 plan, valuables such as jewellery, watches, and antiques are subject to a limit of S$2,500 per article and S$5,000 in aggregate per event. Items such as cameras, laptops, audio and video equipment, musical instruments, and bicycles are covered up to 3% of the Section 1 Benefit Limit per article.
For example, on a Silver-tier plan with S$100,000 contents coverage, the per-article cap on these items would be S$3,000.
High-Value Cap
Similar to the single-article limit, policies also feature a cap on high-value items as a group.
This category usually includes luxury goods such as fine art, wine collections, expensive jewellery, heirlooms, and other rare, valuable possessions.
Even if your overall contents coverage is S$100,000, the sub-limit for luxury valuables may be only a fraction of that amount.
Wear and Tear
Insurance is built to protect you against sudden, unforeseen accidents and disasters. It is not a maintenance contract.
Therefore, our policies do not cover normal wear and tear that happens over time.
For example, if your sofa fabric becomes frayed after years of use, or if your old washing machine stops spinning due to mechanical age, you cannot file a claim. You are responsible for the general upkeep of your household items.
Belongings Outside the Home
Your standard house contents insurance is primarily designed to protect items within your residence. Normally, if you take your laptop to a local café and leave it behind, or if someone steals your smartphone while you are commuting, your contents insurance will not cover the incident.
However, our Home Protect360 insurance can help cover your valuables, even when they are outside your home. Our policy comes with optional Personal Effects coverage, which insures your personal belongings up to S$20,000, S$50,000, or S$70,000, depending on your chosen tier, with a per-article sub-limit.
Also, if your home has been left uninhabitable, you can move your contents, such as furniture, electronics, and appliances, to a temporary storage facility. We cover this scenario, so you can still secure your belongings even while they’re not in your home. Your home contents will still be insured under your Home Protect360 policy, even while they’re in this temporary storage.
Get Comprehensive Home Contents Insurance Today!
Do not wait for a burst pipe or a sudden fire to realise the true value of your possessions. Protecting your household goods should be a top priority for every homeowner and tenant in Singapore.
At HL Assurance, we offer Home Protect360 to give you the comprehensive protection you deserve. Our plan goes beyond basic coverage by safeguarding your household contents against unpredictable accidents.
When you choose our protection, you also gain access to our home assistance concierge services. This means you can reach out to us for immediate assistance with home repairs, whether you need an electrician, plumber, locksmith, or pest control expert.
Take control of your home protection. When in doubt, you can chat with us at HLAS to find out more, at 6702 0202 or email service@hlas.com.sg.
Frequently Asked Questions
How do I calculate the total value of my home contents?
To estimate your total coverage needs, walk through each room and create an inventory of your belongings. Write down what it would cost to replace each item at today’s retail prices, not what you originally paid for them. Don’t forget to include smaller items that add up quickly, such as clothes and collections like books, wine, and trading cards.
What is the difference between “New-for-Old” and “Market Value” coverage?
New-for-old covers the cost of replacing your damaged or stolen item with a brand-new equivalent, regardless of its age.
Market Value (or Actual Cash Value) pays out the value of the item at the time of the loss, meaning the payout will be deducted for age, wear, and tear (depreciation).
Does contents insurance cover my possessions if I am moving to a new house?
If you are relocating within Singapore, contents in transit are usually not covered by standard home contents policies. We recommend checking whether your moving company provides goods-in-transit insurance, or speaking with us about temporary endorsement options.
Does I need contents insurance if I’m renting in Singapore?
Yes. As a tenant, you don’t own the building structure, but you do own everything inside the rented unit, your furniture, electronics, clothing, and personal valuables. If a fire, theft, or burst pipe causes damage, your landlord’s insurance won’t cover your belongings. A house contents insurance plan like our Home Protect360 protects your possessions and provides third-party personal liability cover for incidents occurring inside the rental unit.
Author
HL Assurance (HLAS) is a licensed general direct insurer in Singapore and a member of the General Insurance Association (GIA). Backed by the Hong Leong Group — a diversified conglomerate spanning banking, financial services, and investments across Asia, Europe, and beyond — HLAS offers a wide range of personal and commercial insurance products, including travel, motor, home, maid, and personal accident insurance. With a track record of award-winning service and a focus on digital accessibility, HLAS is dedicated to helping individuals and businesses in Singapore protect what matters most.

 Malaysia
 Hong Kong